
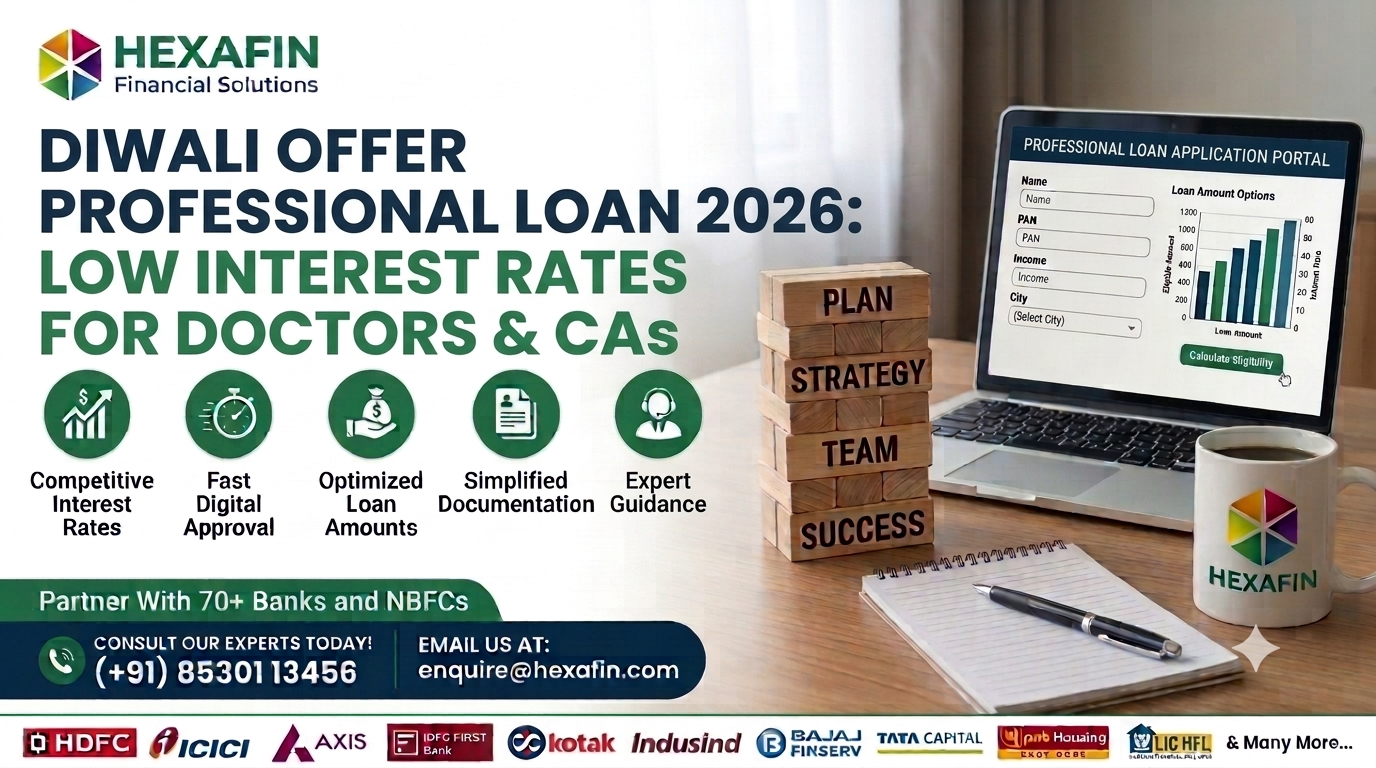
Diwali Offer Professional Loan 2026: Low Interest Rates for Doctors & CAs
Securing an optimal Professional Loan During Diwali Festive Season of 2026 is one of the most strategic financial moves for qualified Doctors, Surgeons, Dentists, Chartered Accountants (CAs), and certified professionals. Whether you are planning to expand your clinical setup, upgrade advanced medical diagnostics equipment, open new CA firm branch offices, procure specialized software, manage practice cash flows, or fulfill personal financial milestones, taking advantage of promotional festive schemes directly safeguards your operational margins.
Today, leading nationalized banks, top private sector lenders, and Non-Banking Financial Companies (NBFCs) introduce specialized Diwali Professional Loan packages—featuring subsidized interest rates, 0% processing fees, elevated sanction limits, and pre-approved instant digital disbursals. However, interest pricing, loan limits, documentation requirements, and tenure flexibilities vary across lending institutions. Conducting a comprehensive comparison before applying can save your practice substantial financing costs over the loan tenure.
If you are searching for Diwali Offer Professional Loan 2026, this detailed guide outlines everything you need to know, including current festive market interest rates, eligibility criteria for Doctors and CAs, lender comparisons, EMI calculation, document requirements, and how Hexafin assists healthcare and financial professionals in securing best-in-class loan terms with expedited approval.
What is a Professional Loan Offer for Doctors & CAs?
A Professional Loan is a customized credit facility tailored exclusively for licensed professionals like Doctors (MBBS, MD, MS, BDS, MDS) and Chartered Accountants holding a valid Certificate of Practice (COP).
During the festive season of Diwali, financial institutions roll out limited-period promotional schemes featuring discounted interest rates, higher credit ceilings, simplified approval workflows, and waived administrative charges.
Since professional qualifications carry an inherently low credit default risk, loan approval and pricing primarily depend on:
-
Medical Council of India (MCI/NMC) or ICAI registration vintage
-
Annual audited turnover and net income statements
-
Personal and Commercial CIBIL score track
-
Years of continuous practice or hospital/firm attachment vintage
-
Existing debt obligations and Debt Service Coverage Ratio (DSCR)
-
Lender’s internal professional credit assessment policy
Festive professional loans can be availed as collateral-free personal/business term loans, medical equipment financing, practice expansion funds, or flexible overdraft limits.
Benefits of Comparing Professional Loan Offers
Evaluating professional loan products across multiple lending institutions prior to application provides clear commercial and personal advantages:
Subsidized Rate Overhead
Securing promotional festive rate reductions helps cut total interest expenses significantly across long repayment tenures.
Zero Processing Fee Schemes
Lenders frequently waive standard processing charges (ranging from 1% to 3%) during Diwali, lowering upfront borrowing costs.
Higher Unsecured Sanction Limits
Doctors and CAs can access higher collateral-free sanction limits (up to ₹50 Lakhs–₹1 Crore) compared to standard personal loans.
Flexible Prepayment Terms
Promotional Diwali offers frequently feature relaxed foreclosure conditions, allowing professionals to prepay funds without penalty when cash flows permit.
Swift Digital Sanctions
Pre-approved digital workflows for doctors and CAs enable quick sanctions with minimal documentation burdens.
Why Compare Professional Loans Before Applying?
Accepting the first available professional loan sanction without market comparison can lead to higher overall borrowing costs and rigid repayment obligations.
A side-by-side comparison allows professionals to analyze:
-
Effective interest rates (Fixed vs. Floating schedules)
-
Special festive processing fee waivers and administrative costs
-
Maximum sanction limits based on professional qualification
-
Flexible tenure choices (12 to 84 months)
-
Monthly EMI obligations
-
Prepayment, foreclosure, and part-payment terms
-
Turnaround time (TAT) from submission to account credit
-
Overall financing costs including hidden service charges
Common Reasons to Apply for a Professional Loan
Doctors and CAs utilize festive professional loan schemes for various operational, expansion, and personal needs, including:
-
Setting up new clinics, multi-specialty hospitals, or diagnostic centers
-
Expanding CA audit firm offices, buying premises, or setting up IT infrastructure
-
Purchasing high-value medical diagnostic tools, ICU equipment, or dental chairs
-
Acquiring specialized accounting, tax compliance, and auditing software systems
-
Managing practice working capital, staff payroll, and seasonal cash flow gaps
-
Refinancing or consolidating high-cost short-term obligations
-
Funding fellowship programs, international medical conferences, or advanced education
-
Personal requirements such as home renovation, wedding expenses, or festive travel
-
Unplanned professional contingencies or emergency cash reserves
Who Can Apply?
Diwali professional loan facilities are accessible to certified professionals across various practice stages.
Doctors & Healthcare Specialists
Including:
-
Medical Practitioners (MBBS, MD, MS) registered with NMC/MCI
-
Dental Surgeons (BDS, MDS) with active clinical practices
-
Super-specialists (DM, MCh, DNB) in private or hospital attachments
-
Ayurvedic, Homeopathic, and Veterinary doctors (BAMS, BHMS, BVSc)
Chartered Accountants & Financial Experts
Such as:
-
Practicing CAs holding an active Certificate of Practice (COP) from ICAI
-
CA firm partners and proprietary practice owners
-
Financial consultants with verified professional track records
Self-Employed & Salaried Professionals
Including:
-
Salaried doctors employed at private/government hospitals or medical colleges
-
Consultant doctors and CAs operating independent offices or clinics
Top Banks Offering Professional Loans (2026)
Leading public sector and private banks offer targeted professional loan solutions with festive discounts.
Popular banking partners include:
-
State Bank of India (SBI)
-
HDFC Bank
-
ICICI Bank
-
Axis Bank
-
Kotak Mahindra Bank
-
IndusInd Bank
-
Bank of Baroda
-
Punjab National Bank
-
Canara Bank
-
Union Bank of India
Banks evaluate applicants using professional credentials, income tax returns, credit scores, and account transaction flows.
Top NBFCs Offering Professional Loans (2026)
Top Non-Banking Financial Companies (NBFCs) provide agile, paperless approvals tailored for Doctors and CAs.
Popular NBFC options include:
-
Poonawalla Fincorp
-
Bajaj Finance
-
Tata Capital
-
Aditya Birla Capital
-
Hero FinCorp
-
L&T Finance
-
SMFG India Credit
-
Clix Capital
-
Moneyview
NBFCs offer flexible eligibility norms and fast-track disbursals for busy healthcare and financial practitioners.
Professional Loan Interest Rates Comparison (Diwali 2026 Special)
Festive rates depend on professional specialization, practice vintage, income stability, and credit score.
| Lender Category | Indicative Festive Rate (p.a.) | Special Processing Fee | Typical Loan Tenure |
| Public Sector Banks | 9.75% – 12.50% | 0.00% – 0.50% (Festive Waivers) | 12 – 84 Months |
| Private Sector Banks | 10.25% – 15.50% | Flat ₹999 to 1.00% | 12 – 60 Months |
| Leading NBFCs | 11.50% – 18.00% | 0.50% – 1.50% | 12 – 60 Months |
| Digital Pre-approved Loans | 9.99% – 14.00% | Nil to Flat Fee | 12 – 60 Months |
Factors Affecting Professional Loan Interest Rates
CIBIL & Commercial Credit Score
A credit score of 750 or higher secures lower interest rates and higher unsecured limits.
Professional Practice Vintage
Doctors and CAs with over 3 to 5 years of continuous post-qualification practice qualify for preferred rate tiers.
Income Track & Financial Statements
Higher net cash flows and consistent profit margins demonstrate stable debt-servicing capability.
Professional Qualification & Degree
Super-specialist doctors (MD/MS/DM) and senior CAs with active COP status often unlock lower risk-premium pricing.
Existing Relationship with Lender
Holding a current or savings account with a bank unlocks pre-approved festive loan offers with instant disbursal.
Loan Amount & Repayment Tenure
Approved Loan Limits
The total professional loan sanction depends on:
-
Annual net income or gross receipts
-
Qualification level and practice experience
-
Fixed Obligations to Income Ratio (FOIR)
-
Existing credit obligations and repayment track
Repayment Tenure Options
-
Short-Term Options (12 to 36 Months): Higher monthly EMIs, lower cumulative interest costs.
-
Long-Term Options (48 to 84 Months): Lower monthly EMIs, higher overall interest outlay.
Selecting an optimal tenure helps balance practice cash flows with minimal total interest charges.
Professional Loan EMI Calculator
Before applying, estimate your monthly repayment commitments using a Professional Loan EMI Calculator.
EMI calculations depend on three key variables:
-
Total principal amount ($P$)
-
Applicable festive interest rate ($R$)
-
Selected repayment tenure ($N$)
Calculating EMIs in advance ensures financial commitments align smoothly with clinic or firm earnings.
Documents Required
While requirements vary by lender and applicant profile, standard professional loan documentation includes:
KYC & Professional Proofs
-
PAN Card (Mandatory)
-
Aadhaar Card / Passport / Driving License / Voter ID
-
Professional Qualification Certificates (Degree/Diploma)
-
Registration Certificate (MCI/NMC for Doctors, ICAI COP for CAs)
-
Business Address Proof (Clinic/Office utility bill or rent agreement)
Financial & Banking Documents
-
Income Tax Returns (ITR) with Computation for the last 2 years
-
Audited Profit & Loss Account and Balance Sheet (for self-employed)
-
Salary slips for the last 3 months (for salaried doctors/CAs)
-
Bank account statements for the last 6 to 12 months
-
Sanction letters and repayment tracks for existing active loans
Why Apply Through Hexafin?
Navigating multiple festive schemes across banks can be time-consuming for busy professionals. Hexafin simplifies borrowing by connecting Doctors and CAs to over 70 top banks and NBFCs through a single consultation.
Hexafin assists professionals in comparing interest rates, verifying pre-approved offers, calculating EMIs, and finalizing loan sanctions smoothly.
Our Loan Services
We assist with:
-
Professional Loan (Doctors & CAs)
-
Business Loan (Unsecured)
-
Working Capital Loan (CC/OD)
Why Borrowers Choose Hexafin
-
Compare 70+ Banks & NBFCs: Access customized professional loan schemes across top institutions via one application.
-
Specialized Consultation: Receive tailored suggestions aligned with medical practice or accounting firm cash flows.
-
Free Pre-Application Eligibility Assessment: Check maximum sanction limits and interest eligibility before formal submission.
-
Doorstep & Digital Support: Receive assistance in collecting, auditing, and filing loan documentation.
-
Expedited Processing: Dedicated team leads coordinate directly with credit managers for quick approvals.
-
Transparent Terms: Gain full clarity on interest rates, processing fee waivers, and foreclosure guidelines.
How to Apply for a Professional Loan Online
The application process follows a simple digital sequence:
-
Step 1: Verify Eligibility – Review professional registration, practice vintage, and current liabilities.
-
Step 2: Compare Rates & Schemes – Evaluate festive interest offers, processing fee waivers, and tenure options.
-
Step 3: Calculate EMI & Select Tenure – Choose a suitable EMI structure matching monthly practice cash flows.
-
Step 4: Upload Documentation – Provide KYC, registration proof, ITRs, and bank statements for verification.
-
Step 5: Credit Assessment & Verification – The credit team reviews professional credentials and financial statements.
-
Step 6: Sanction & Account Credit – Sign the digital loan agreement and receive direct funds transfer.
Apply for a Professional Loan Online Today
Whether you are expanding a medical practice, setting up a new CA office, purchasing advanced machinery, or managing personal expenses, comparing lenders during the festive season ensures optimal loan terms in 2026.
Why Choose Hexafin?
-
✅ Compare 70+ Top Banks & NBFCs
-
✅ Tailored Advisory for Doctors & CAs
-
✅ Free Pre-Application Eligibility Checks
-
✅ End-to-End Documentation Assistance
-
✅ Custom Financing Solutions
-
✅ Expedited Sanction & Direct Disbursement
Book your FREE Consultation with Hexafin today. Let our loan experts help you compare rates, calculate EMIs, check pre-approved offers, and finalize your professional loan application with ease.
Frequently Asked Questions (FAQs)
1. What are the average professional loan interest rates for Doctors and CAs in 2026?
During Diwali 2026, professional loan interest rates start from 9.75% to 12.50% per annum at leading public sector banks, and between 10.25% and 18.00% per annum across private banks and NBFCs, depending on professional experience and credit history.
2. Is collateral required for a professional loan for Doctors or CAs?
No. Unsecured professional loans do not require property or security. Approval is granted based on professional registration (MCI/NMC/ICAI), income history, CIBIL score, and practice cash flows.
3. Can I get a 0% processing fee offer on a professional loan during Diwali?
Yes. Several banks and NBFCs offer 0% processing fee schemes or flat fee discounts during Diwali promotional drives for qualified professionals.
4. How fast can a professional loan be disbursed?
Pre-approved digital professional loans can be sanctioned and disbursed within 24 to 48 hours following document upload and verification.
5. What minimum CIBIL score is needed for a Doctor or CA loan?
A CIBIL score of 750 or higher is recommended to unlock the lowest interest rates, zero processing fees, and elevated sanction limits.
6. Does Hexafin charge any fee for professional loan consultation?
No. Hexafin provides initial professional loan eligibility checks and consultations completely free of cost.
Conclusion
Securing the best Diwali professional loan offer in 2026 requires comparing interest rates, processing fee waivers, sanction limits, and repayment terms across multiple lenders.
With Hexafin, Doctors and CAs can evaluate schemes from over 70 top banks and NBFCs, obtain guidance, streamline paperwork, and select a professional loan aligned with their practice goals.
📞 Need Expert Guidance for Your Professional Loan?
To check your profile eligibility and secure competitive loan rates this festive season, connect with Hexafin experts today:
-
📧 Email Us: enquiry@hexafin.com
-
📞 Call Us: +91 8530113456
-
💬 WhatsApp Us: Chat on WhatsApp