
Loan Against Property in Delhi (2026): Compare Interest Rates, Eligibility & Apply Online
Applying for a Loan Against Property (LAP) in Delhi has become one of the most effective ways to raise high-value capital at competitive interest rates. Whether you require funds to expand your business operations, inject working capital, fund higher education abroad, manage high medical costs, renovate real estate, or consolidate existing high-cost loans, a Property Mortgage Loan allows you to unlock the hidden equity in your residential, commercial, or industrial property without losing ownership.
Since LAP is a secured credit facility, leading banks and NBFCs offer substantially lower interest rates and longer repayment tenures compared to unsecured personal or business loans. However, loan-to-value (LTV) limits, legal verification procedures, interest rates, and eligibility policies differ significantly across financial institutions.
If you are looking to apply for a Loan Against Property in Delhi (2026), this comprehensive guide covers everything you need to know, including current interest rates, eligibility criteria, property documentation, EMI calculations, top partner banks, leading NBFCs, local coverage across Delhi NCR, and how Hexafin assists you in securing the best mortgage deal.
What is a Loan Against Property (LAP)?
A Loan Against Property (LAP)—commonly known as a Mortgage Loan—is a secured loan facility where a fully constructed residential, commercial, or industrial property is pledged as collateral with a financial institution.
Since the lender maintains legal charge over the asset until full repayment, approval primarily depends on:
Market value and legal title clarity of the property
Loan-to-Value (LTV) ratio (typically 50% to 75% of market value)
Borrower’s net monthly income or audited business cash flows
Credit history and CIBIL score
Debt-to-income balance (FOIR ratio)
Overall repayment capacity
Borrowers retain full physical possession and operational control of the pledged property throughout the loan tenure.
Benefits of Applying for a Loan Against Property
Mortgage loans offer distinct financial advantages over unsecured credit products.
High Sanction Amount
Access high-value capital ranging from ₹10 Lakhs to ₹10 Crores+ based on the appraised market value of your property.
Significantly Lower Interest Rates
Since the loan is backed by tangible real estate, interest rates are considerably lower than personal loans or credit cards.
Extended Repayment Tenure
Flexible repayment structures ranging from 5 to 20 years ensure manageable and budget-friendly monthly EMIs.
Multi-Property Acceptance
Lenders accept residential flats, builder floors, self-constructed houses, commercial office spaces, retail shops, and industrial properties in Delhi NCR.
Unrestricted Capital Use
Sanctioned funds can be used for any legitimate business, commercial, Educational, Personal, or debt-consolidation requirement.
Flexible Overdraft (OD) Options
Many partner institutions offer Dropline Overdraft or LAP OD facilities where interest is charged only on the funds utilized.
Why Compare LAP Offers Before Applying?
Locking into a mortgage loan without evaluating market options can result in higher long-term interest burdens and restrictive terms.
Comparing multiple lenders allows you to evaluate:
Interest rate structure (Floating Repo-linked vs. Fixed)
Maximum Loan-to-Value (LTV) percentage offered
Legal and technical verification fees
Processing charges and administrative costs
Prepayment and foreclosure charge policies
Overdraft vs. Term Loan flexibility
Property acceptance norms (unapproved layouts, lal dora, or joint ownership)
Speed of sanction and property valuation turnaround
A thorough market comparison ensures you obtain optimal funding while protecting your property’s equity.
Common Reasons to Apply for a Loan Against Property
Borrowers in Delhi utilize LAP for diverse financial and capital expansion objectives, including:
Business expansion, machinery acquisition, and inventory purchasing
Infusing long-term working capital into business operations
Consolidating high-cost short-term business or personal debts
Commercial property or office space expansion
Funding overseas education and professional courses
Conducting major home renovation, extension, or building upgrades
Managing wedding, family event, or emergency medical costs
Commercial real estate investment or lease discounting
Other legitimate personal or commercial funding needs
Who Can Apply?
Loan Against Property facilities are available to a broad spectrum of individual and corporate borrowers in Delhi.
Salaried Employees
Including professionals employed with:
Private limited firms and multinational corporations (MNCs)
Central and State Government departments & PSUs
Educational, medical, and public service institutions in Delhi NCR
Self-Employed Professionals
Such as:
Doctors, surgeons, and healthcare facility owners
Chartered Accountants (CAs) and financial consultants
Architects, civil engineers, and interior designers
Lawyers and legal advocates
Business and IT consultants
Self-Employed Individuals & Business Owners
Including:
Sole proprietors, partners, and private company directors
Retailers and traders in Chandni Chowk, Sadar Bazar, and Connaught Place
Industrialists operating in Okhla, Mayapuri, Mangolpuri, and Wazirpur
Service providers, wholesalers, and logistics operators
Eligibility rules vary depending on individual lender policies and property characteristics.
Top Banks Offering Loan Against Property in Delhi
Leading public and private sector banks offer competitive mortgage solutions in Delhi NCR.
Popular bank partners include:
HDFC Bank
ICICI Bank
Axis Bank
Kotak Mahindra Bank
IDFC FIRST Bank
IndusInd Bank
State Bank of India (SBI)
Punjab National Bank (PNB)
Canara Bank
Union Bank of India
Bank of Baroda
Bank of Maharashtra
Each bank evaluates applications based on income stability, property legalities, technical valuation, and internal risk policies.
Top NBFCs Offering Loan Against Property in Delhi
Leading Non-Banking Financial Companies (NBFCs) provide flexible mortgage frameworks, higher LTVs, and customized underwriting policies.
Popular NBFC partners include:
Bajaj Finance
Tata Capital
Aditya Birla Finance
Poonawalla Fincorp
Hero FinCorp
L&T Finance
IIFL Finance
SMFG India Credit
Clix Capital
Moneyview
NBFCs frequently cater to unique business income profiles, non-standard property document sets, and flexible credit evaluation requirements.
Interest Rates & Factors Affecting Approval
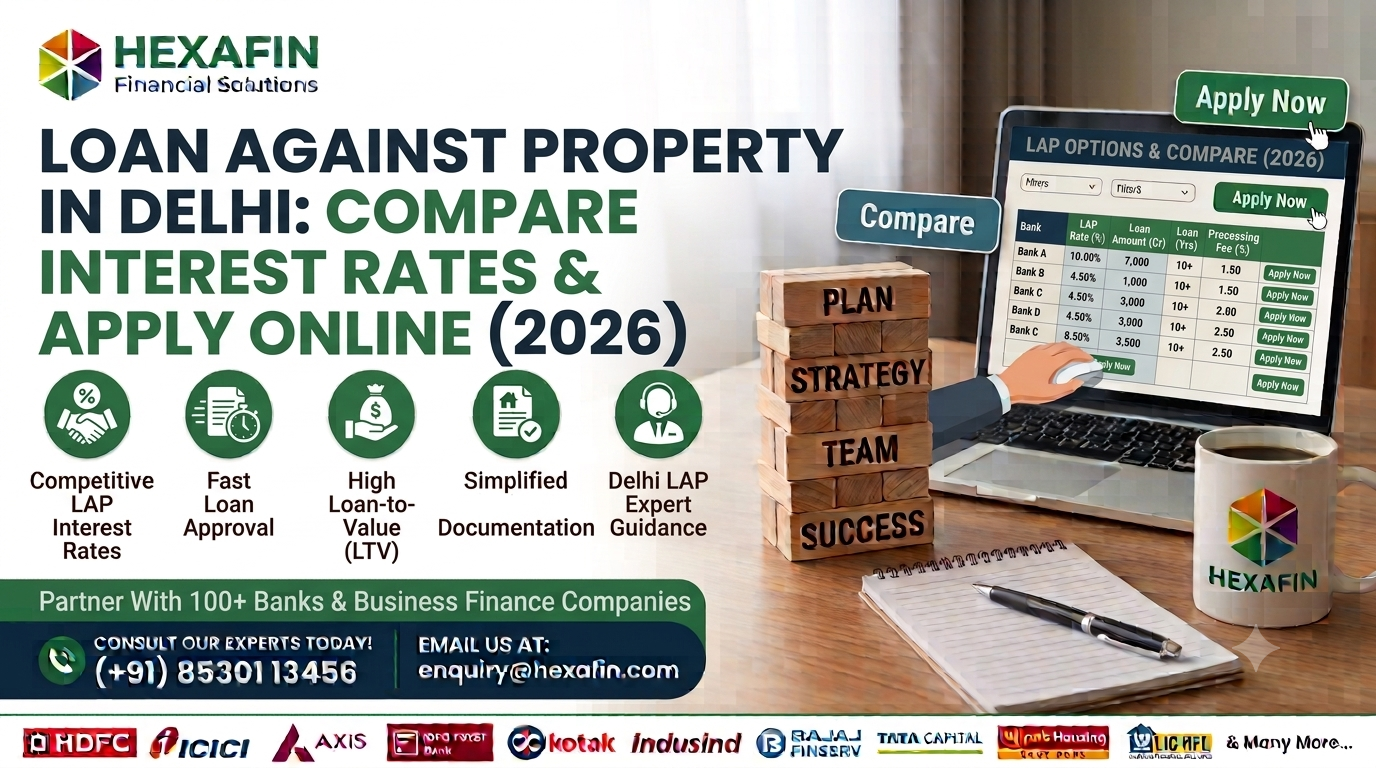
Interest rates for Loan Against Property typically range from 8.50% to 12.50% p.a. depending on profile risk and property category.
Key Factors Influencing Interest Rates & Approval:
Credit score (CIBIL score of 700+ preferred)
Type of property (Residential properties generally get lower rates than Commercial/Industrial)
Property location, usage, title clarity, and age of structure
Sanctioned Loan-to-Value (LTV) ratio
Net income, audited turnover, and repayment capacity (FOIR)
Employment or business vintage
Borrower’s existing debt profile
Comparing options across multiple lenders with Hexafin ensures you secure the lowest applicable interest rate for your specific property.
Loan Amount & Repayment Tenure
Sanctioned Loan Quantum
Loan Amount: Ranges from ₹10 Lakhs up to ₹10 Crores or more.
LTV Limit: Lenders generally sanction between 50% and 75% of the property’s appraised market value.
Repayment Tenure Structure
Available Tenure: Ranges from 5 years up to 20 years.
Tenure Impact: Longer tenures yield lower monthly EMIs, reducing cash flow strain. Shorter tenures lower the overall interest paid over the life of the mortgage.
Loan EMI Calculator
Before applying, estimate your monthly cash outflow using a Loan Against Property EMI Calculator.
EMI values depend on three variables:
Total loan principal amount
Applicable annual interest rate
Selected loan tenure (in months)
Calculating EMIs beforehand helps plan your financial obligations while keeping business or personal cash flows balanced.
Documents Required
Properly organized paperwork accelerates the legal and technical approval process.
Personal & KYC Documents
Identity Proof: PAN Card (Mandatory), Aadhaar Card, Passport, Driving Licence
Address Proof: Aadhaar Card, Recent Utility Bills, Registered Rent Agreement
Financial & Income Proof
Salaried Applicants
Latest 3–6 months Salary Slips
Last 6 months Bank Statements (Salary account)
Form 16 / Income Tax Returns for the last 2 years
Self-Employed / Business Applicants
Income Tax Returns (ITR) with Computation for the last 3 financial years
Audited Balance Sheet and Profit & Loss Statement
12 months Bank Account Statements (Current & Savings)
Business Registration Proof (GST Certificate, Partnership Deed, Certificate of Incorporation, MSME/Udyam)
Property-Related Documents
Chain of Title Deeds / Sale Deed / Conveyance Deed
Approved Building Plan & Possession Certificate/Occupancy Certificate
Property Tax Receipts and Allotment Letter (where applicable)
Encumbrance Certificate (EC) and NOC from Society/Authority
Why Apply Through Hexafin? & Our Services
Partnering with Hexafin simplifies the mortgage journey by giving you access to 70+ banks and NBFCs through a single dedicated loan specialist.
Hexafin assists with pre-eligibility checks, legal verification coordination, property valuation tracking, and end-to-end file processing.
Our Loan Services
We assist clients with:
Commercial Property Loan
Step-by-Step How to Apply Process
Applying for a Loan Against Property through Hexafin follows six clear steps:
Step 1: Free Eligibility & Property Assessment – Evaluate income, property value, and basic title requirements.
Step 2: Multi-Bank Offer Comparison – Compare interest rates, LTVs, processing fees, and terms across top banks and NBFCs.
Step 3: Document Collection – Provide required KYC, income, and complete property title documents.
Step 4: Legal & Technical Valuation – The chosen lender conducts physical property appraisal and legal title search.
Step 5: Credit Sanction & Approval – The lender issues a formal sanction letter detailing loan amount, rate, and conditions.
Step 6: Agreement Execution & Disbursement – Execute mortgage documentation, deposit original title deeds, and receive funds directly in your bank account.
Local Area Coverage Across Delhi
Hexafin offers localized consultation, property guidance, and doorstep documentation support across all major zones and commercial hubs in Delhi NCR, including:
South Delhi: Saket, Hauz Khas, Vasant Kunj, Greater Kailash, Lajpat Nagar, Defence Colony
Central Delhi: Connaught Place, Karol Bagh, Rajendra Nagar, Patel Nagar
West Delhi: Janakpuri, Rajouri Garden, Punjabi Bagh, Dwarka, Paschim Vihar
North Delhi: Rohini, Pitampura, Model Town, Civil Lines, Shalimar Bagh
East Delhi: Preet Vihar, Laxmi Nagar, Mayur Vihar, Shahdara
Industrial & Commercial Belts: Okhla Industrial Area, Mayapuri, Mangolpuri, Wazirpur, Kirti Nagar, Naraina
Conclusion
A Loan Against Property in Delhi provides a powerful, cost-effective financial route for securing large capital while preserving asset ownership. However, navigating property valuations, legal title checks, LTV caps, and interest rate structures requires expert guidance.
With Hexafin, borrowers gain direct access to 70+ leading banks and NBFCs, expert property advisory, smooth documentation support, and complete clarity to secure the best mortgage loan tailored to their financial objectives.
Frequently Asked Questions (FAQs)
1. Can I get a loan against a commercial property in Delhi?
Yes. Banks and NBFCs offer Loan Against Property on residential flats, independent houses, commercial offices, retail shops, and approved industrial properties.
2. How much loan amount can I get against my property?
Lenders typically offer 50% to 75% of the property’s current market value (LTV), subject to income evaluation and repayment capacity.
3. Can I prepay or foreclose a floating rate LAP without charges?
Yes. As per RBI directives, individual borrowers taking floating-rate loans for non-business purposes face zero foreclosure or part-prepayment penalties. Business-purpose or fixed-rate loans may carry nominal charges as per lender policy.
4. How long does it take to disburse a Loan Against Property?
Because LAP involves physical technical valuation and detailed legal title searches, disbursal generally takes between 7 to 14 working days from document submission.
📞 Need Expert Guidance for Your Loan?
Aapke profile ke acche approval rates aur sabse kam interest rate ke liye aaj hi Hexafin ke financial experts se connect karein:
📧 Email Us: enquiry@hexafin.com
📞 Call Us: +91 8530113456
💬 WhatsApp Us: Chat on WhatsApp